
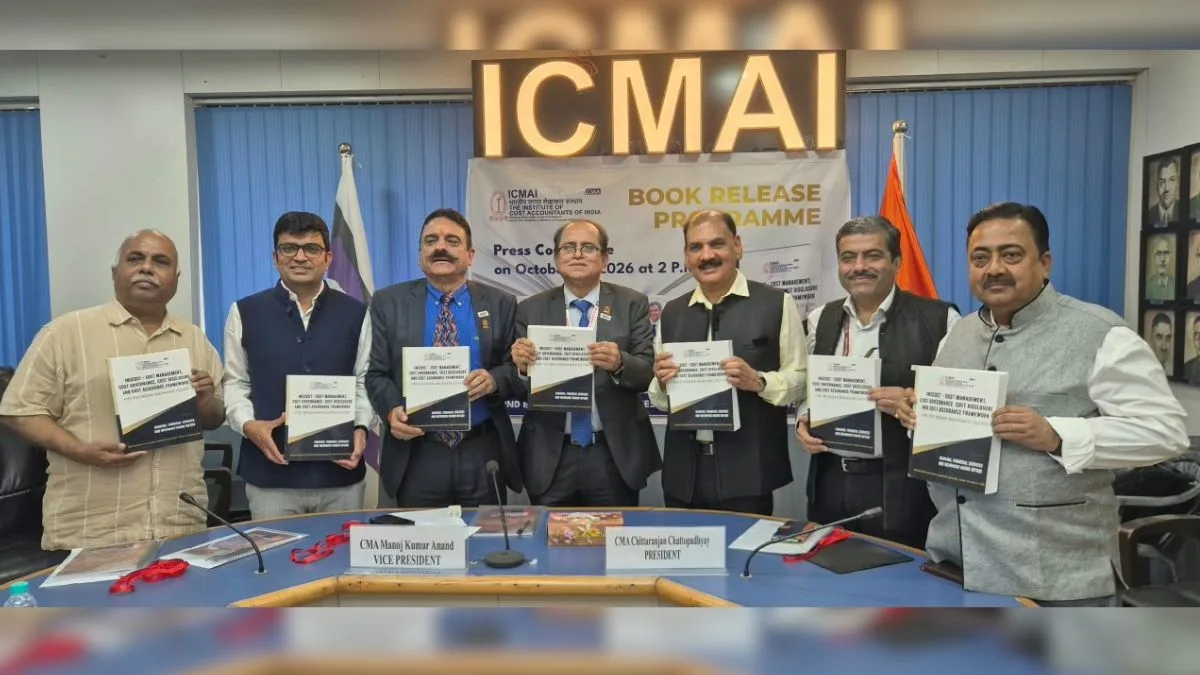
ICMAI has unveiled INSCOST, a sector-specific framework covering insurance cost management, disclosure, governance, assurance and product profitability
New Delhi: The Institute of Cost Accountants of India (ICMAI) has unveiled a new framework aimed at improving cost management and governance in the Indian insurance sector. Called INSCOST, the framework covers cost management, cost governance, cost disclosure and cost assurance.
The INSCOST Framework marks the first edition of ICMAI’s sector-specific guidance for insurance. It covers major segments including life, general, health, reinsurance and public-sector insurance.
According to ICMAI, the framework aims to give insurers a structured approach to managing costs while improving transparency and decision-making. It also addresses strategic cost management and product profitability.
What Does the INSCOST Framework Cover?
The framework adapts ICMAI’s existing Cost Accounting Standards, Cost Auditing Standards and Generally Accepted Cost Accounting Principles to the insurance sector.
It also considers the regulatory framework of IRDAI and provides guidance on several insurance-specific cost areas. These include:
- Cost allocation
- Expenses of Management
- Claims-related costs
- Distribution costs
- Bancassurance
- Government-sponsored insurance schemes
- Strategic cost analytics
- Product profitability
ICMAI said insurers need to consider cost management alongside claims management. Controlling acquisition, procurement and operational expenses can help insurers improve efficiency and strengthen profitability.
Cost Management as a Governance Tool
The framework treats cost information as more than an accounting requirement. It encourages insurers to use cost data as a management and governance tool.
Insurers can use the framework to assess the factors driving their expenses, identify inefficient processes and examine whether product costs match the value delivered to customers.
ICMAI President CMA Chittaranjan Chattopadhyay said stronger cost management can play an important role as India works towards Insurance for All by 2047.
Vice President CMA Manoj Anand said reliable cost information can help insurers make better decisions at product, process and operational levels.
Framework Includes Cost Maturity Model
INSCOST also introduces a Cost Maturity Model and a phased implementation roadmap. Insurers can use the model to gradually improve their cost management and assurance practices according to their size and preparedness.
The framework also expands the potential role of Cost and Management Accountants in the insurance industry. Their work can include product-level profitability analysis, claims cost assessment, distribution cost management, budgeting, process optimisation and strategic decision-making.
The framework comes at a significant time for the industry. On September 23, 2026, IRDAI issued a public consultation paper on ‘Reforms for Recalibrating Economics of Insurance Distribution’. The proposals have relevance for areas such as commission structures, Expenses of Management, cost rationalisation and transparency.
ICMAI said the INSCOST Framework can help insurers and other stakeholders build stronger cost governance systems and support the development of more efficient insurance products.


